A CD ladder sounds like a finance-pro move, but building one is genuinely just five steps you can do in an afternoon. It gives you higher long-term rates and access to part of your money every year — the best of both worlds. Here’s the exact process.
Quick answer: split your money into equal parts, open CDs with staggered terms (1, 2, 3, 4, 5 years), and reinvest each one into a new long-term CD as it matures. Within a few years, one CD matures every year at top rates. Plan yours with our free CD Ladder Calculator.
Step 1: Decide Your Total and Number of Rungs
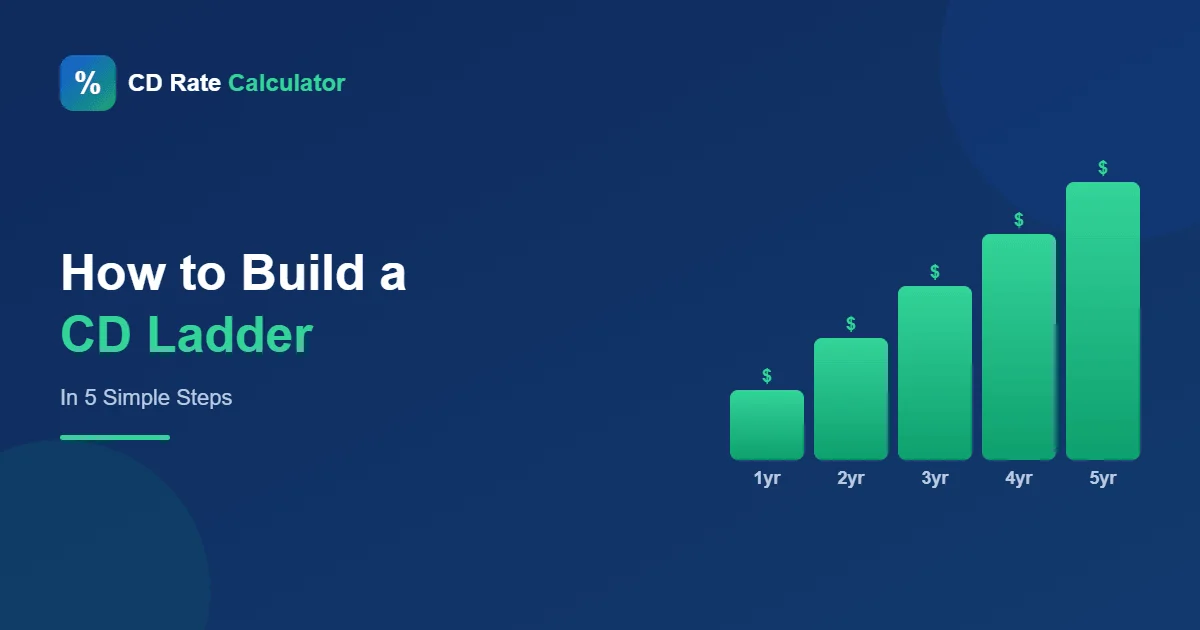
Pick the amount you can commit and divide it into equal “rungs.” Five rungs is the classic setup; three works fine for smaller amounts. Let’s use $25,000 split into five $5,000 rungs as our example throughout.
Step 2: Open CDs With Staggered Terms
Open all your CDs at once, each with a different term:
| Rung | Deposit | Term |
|---|---|---|
| 1 | $5,000 | 1 year |
| 2 | $5,000 | 2 years |
| 3 | $5,000 | 3 years |
| 4 | $5,000 | 4 years |
| 5 | $5,000 | 5 years |
You can open them all at one bank for simplicity, or shop the best rate for each term across banks (usually earns more).
Step 3: When a CD Matures, Reinvest It at the Top
After year one, your 1-year CD matures. Roll that money into a new 5-year CD. A year later, the original 2-year CD matures — roll it into another new 5-year CD. Keep repeating. Watch the maturity dates closely (our maturity date calculator helps) so you act during the grace period and never get auto-renewed at a poor rate.
Step 4: After 4 Years, the Ladder Is “Mature”
From this point on, every rung is a 5-year CD earning top long-term rates — but one still matures every single year. That’s the magic: full long-term yield plus yearly access to 20% of your money. Miss a rate you like? You’re never more than 12 months from a maturity.
Step 5: Adjust as Life Changes
When a rung matures, you’re not forced to reinvest — spend it, add to it, or change the plan. If rates are falling, the ladder already locked most of your money at higher rates. If rates are rising, each maturing rung captures the new higher rate. Either way, you never have to guess the market. See the full logic in our CD ladder strategy guide.
Ladder Variations
- Mini ladder: 6, 12, and 18-month CDs — access every six months, good for short horizons.
- Long ladder: 1 through 10 years for maximum long-term yield (uses longer-term CDs).
- Uneven ladder: put more money in the terms with the best rates — nothing forces equal rungs.
FAQ
How much money do I need to build a CD ladder?
No official minimum — if your bank offers $500 CDs, you can build a 3-rung ladder with $1,500. The strategy works identically at any size.
What’s the benefit of a CD ladder over one big CD?
Access and flexibility. Part of your money frees up every year penalty-free, while most of it still earns long-term rates. You also reprice a portion each year as rates change.
Should I build a ladder when rates are falling?
Yes — falling rates are a strong argument for laddering now, because your longer rungs lock today’s higher rates for years.
Can I build a CD ladder at one bank?
Yes, and it’s simpler to manage. But shopping each rung across banks usually earns more, since no single bank has the best rate for every term.
Map out your own ladder in seconds — free CD Ladder Calculator.